1. What Is a Growth-Focused Property?
A growth-focused property prioritises long-term capital appreciation. These properties are typically located in:- High-demand suburbs
- Areas with strong owner-occupier appeal
- Middle-ring and inner-ring markets
- Locations with strong fundamentals such as schools, transport, lifestyle, and employment hubs
Common characteristics of growth properties
- High land value component
- Strong demographic profiles
- Tight supply and rising demand
- Consistent 10 plus year growth history
- Vacancies consistently below 2 percent
- Higher price points and usually lower yields
2. What Is a Yield-Focused Property?
A yield-focused property prioritises rental income and cashflow stability. Yield assets are typically found in:- Regional areas
- More affordable outer suburbs
- High-rental-demand markets
- Lower entry-price locations
Common characteristics of yield properties
- Higher gross yield of 4.5 percent to 6 percent or more
- Lower purchase prices
- Strong rental competition
- Less capital growth than premium areas
- Often in regional or fringe metro suburbs
We assess every property with Presm 150, our 150-point framework
Find out what that looks like for your budget.
3. Growth vs Yield in 2026: What’s Changed?
The Australian market in 2026 is shaped by several key forces.1. Tighter lending restrictions
Banks are more conservative with borrowing capacity. Growth assets can restrict borrowing faster, while yield can support serviceability.2. High competition for investment-grade property
Investors are hunting for limited stock in high-growth suburbs, increasing pressure on prices.3. Rental demand at record highs
Yields have improved across many markets due to supply shortages.4. Inflation and interest rates remain a factor
Cashflow risk matters more today than it did five years ago.5. Long-term performance still favours growth
Historically, capital cities and high-demand suburbs continue to outperform over decades. This is why the old “growth vs yield” debate doesn’t work anymore. In 2026, it’s about which strategy gets you to your next purchase.4. Pros and Cons of a Growth Strategy
Benefits
- Higher long-term wealth creation
- Strong capital appreciation
- More equity to refinance and reinvest
- Works exceptionally well across multiple cycles
- Ideal for building multi-property portfolios
Risks and limitations
- Lower rental yield
- Higher holding costs
- Can pressure borrowing capacity
- Requires strong serviceability
- More sensitive to interest rate increases
5. Pros and Cons of a Yield Strategy
Benefits
- Better cashflow stability
- Supports borrowing capacity
- Lower financial pressure during high-rate periods
- Easier to hold long-term
- Good for investors needing income
Risks and limitations
- Lower capital growth
- Less equity creation
- Harder to scale a portfolio quickly
- Vulnerable to regional economic shifts
- May underperform in weaker markets
6. Which Strategy Is Better in 2026?
The answer depends on your goals, your finances, and your timeline. Use this framework.Choose a Growth Strategy if
- You want to build a multi-property portfolio
- You have strong household income
- You can comfortably handle negative cashflow
- Your goal is long-term wealth rather than short-term income
- You prioritise equity creation over yield
Choose a Yield Strategy if
- You need stronger cashflow support
- Your borrowing capacity is tight
- You want lower-risk holding costs
- You prefer income stability
- You are earlier in your investing journey and need serviceability
7. The Hybrid Strategy
The most effective investors don’t choose between growth and yield. They combine both in the right order. A smart hybrid strategy often looks like:- Start with growth to build equity early
- Add yield to support borrowing capacity and holding costs
- Return to growth once the portfolio stabilises
- Rotate between both based on your long-term roadmap
8. Real-World Example: Growth vs Yield Outcomes
Scenario A: Growth-Focused Purchase
- Lower yield
- Strong long-term compounding
- Equity-rich outcomes
- Enables more purchases
Scenario B: Yield-Focused Purchase
- Higher cashflow
- Slower growth
- Equity builds more slowly
- Borrowing capacity lasts longer
9. The Biggest Mistake Investors Make in 2026
Choosing a property based on emotion instead of strategy. Growth and yield are tools, not identities. A growth asset in the wrong portfolio can be harmful. A yield asset in the wrong portfolio can slow progress. Your strategy should determine the property, not the other way around.Why Cash-Flow-Positive Properties Often Underperform
Yield is rent divided by price, so a property that looks cheap on yield is often cheap for a reason. A high yield can signal thinner demand, more risk, or a ceiling on long-term price growth.
- Demand quality matters more than yield. Growth is usually driven by deep, competitive demand, especially from owner-occupiers. Markets that rely on investors or a narrow tenant base can be more vulnerable when conditions tighten.
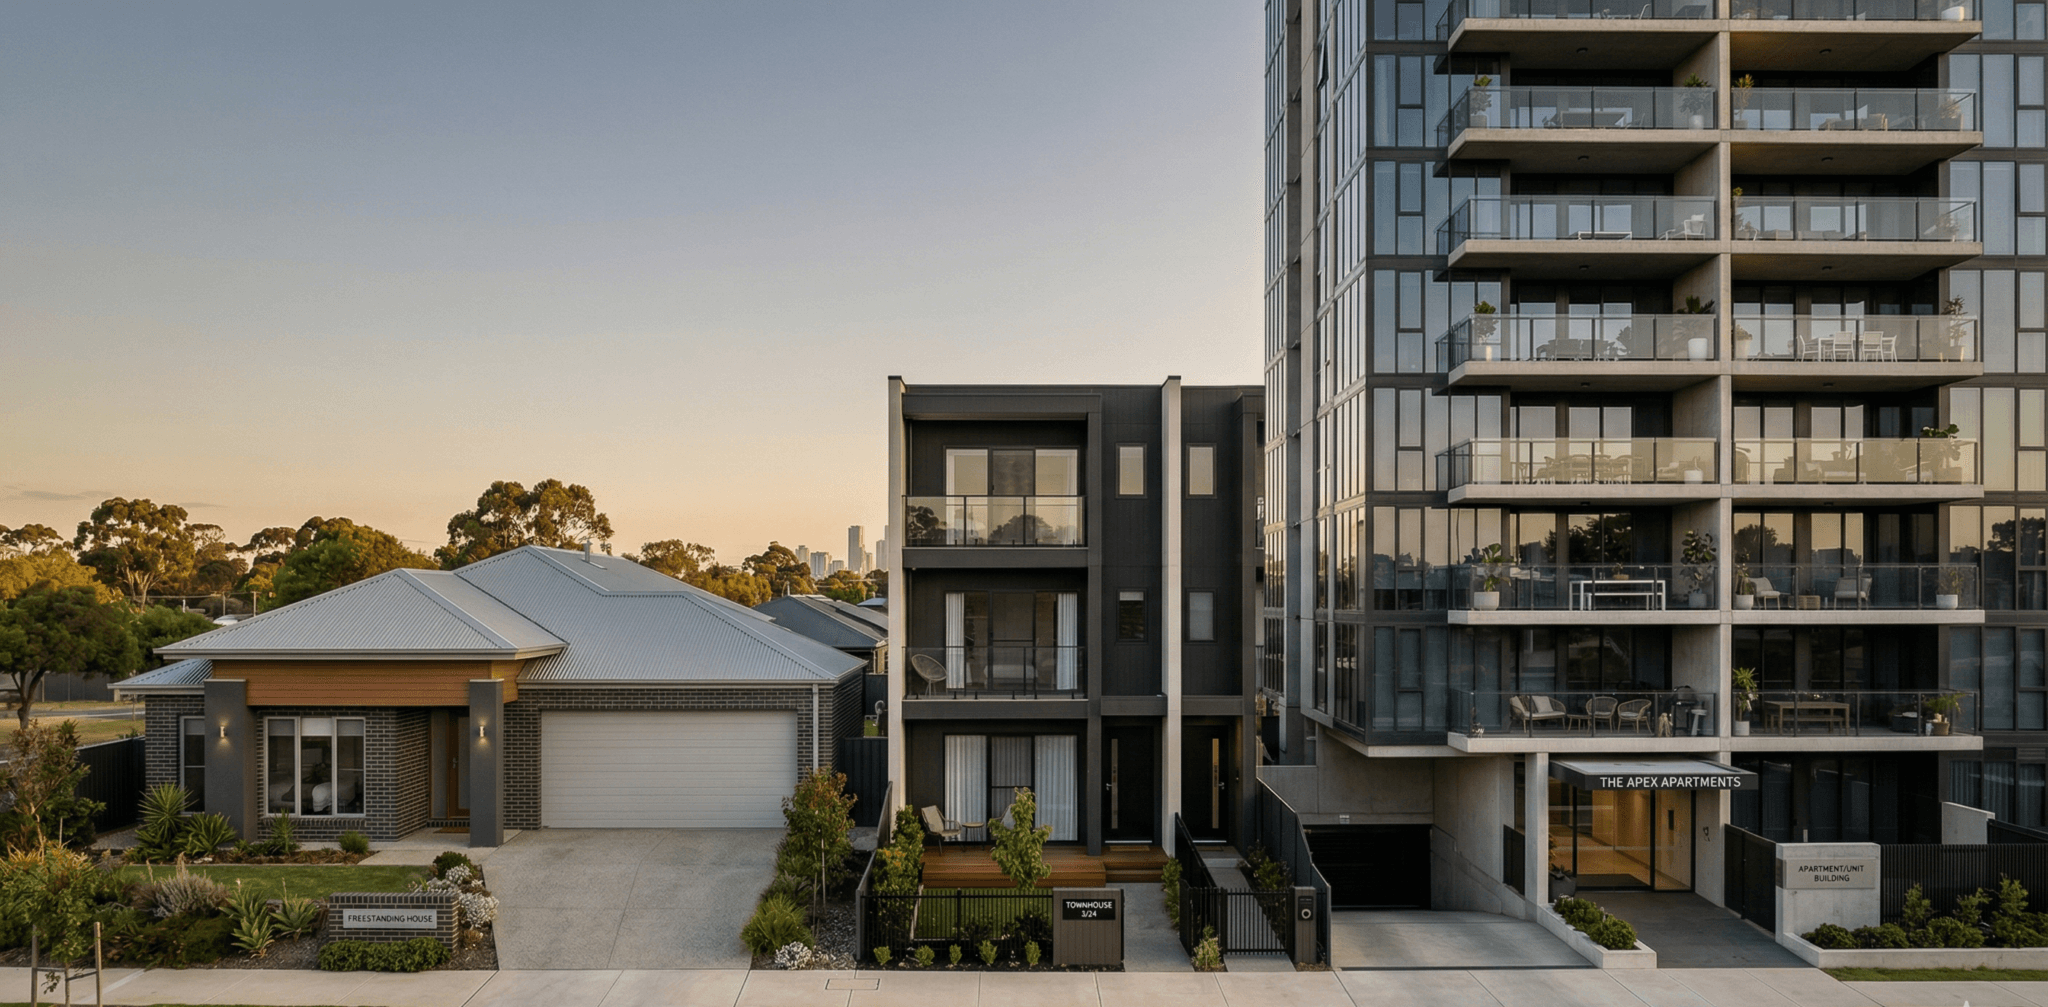
- Easily replicated stock limits growth. High-yield property is often plentiful, such as fringe house-and-land packages or high-density units. When new supply can be added easily, scarcity is weak.
- Rent does not lift borrowing capacity as much as investors expect. Lenders usually count only part of the rent when assessing a loan, to allow for vacancies and costs.
Yield still has a place. In the income phase of life, or to balance a portfolio of growth assets, steady net income can matter more than maximum growth. The mistake is making yield the first filter.
Final Thoughts
Growth vs yield isn’t a battle. It’s a blueprint. In 2026, growth builds wealth, yield supports your ability to hold, and a strategic mix compounds long-term success. The best investors aren’t choosing between growth or yield. They’re choosing the strategy that moves their portfolio forward. When you understand your borrowing capacity, cashflow position, risk tolerance, and long-term goals, the right strategy becomes obvious. If you want help mapping the right approach for your position, book a FREE discovery call.
Written by
Mossy Taheri is the founder and director of Rising Returns, a licensed buyers agency. He has 11 years in the property industry and leads the research behind every purchase, from market selection to negotiation.
Rising Returns is a licensed buyers agency, not a financial adviser, and does not hold an Australian Financial Services Licence. This article is general information only, not financial, tax or legal advice. It does not take into account your objectives, financial situation or needs. Consider seeking advice from a licensed financial adviser, accountant or lawyer before acting.