We are not financial advisers. This article mentions financial products such as super, SMSFs, shares or investment loans. It is general information only, not a recommendation to set up, buy, sell or switch any financial product. Speak to a licensed financial adviser about your own situation.
Welcome to our comprehensive walkthrough for property owners on how to leverage debt recycling to expedite your wealth accumulation journey.
What is Debt Recycling?
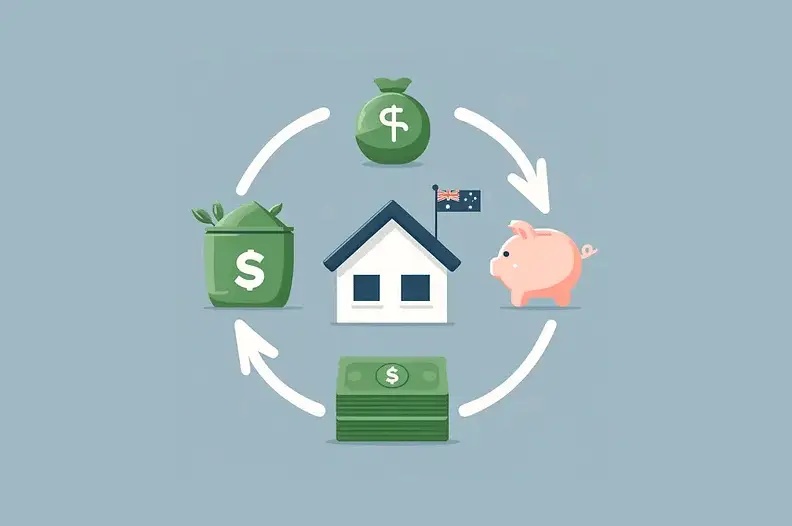
Debt recycling stands as a progressive financial strategy that involves the replacement of non-deductible home loan debt with deductible investment debt. This sophisticated technique not only aids in mitigating your home loan quicker but also equips you to tap into income-producing investments that can foster your tax deductions.
Why Consider Debt Recycling?
The primary advantage of this strategy is its ability to catalyze your investment potential, which might otherwise necessitate extensive saving periods. By adopting debt recycling, you can initiate additional income sources and leverage each tax deduction available.
We assess every property with Presm 150, our 150-point framework
Find out what that looks like for your budget.
Understanding the Strategy
The essence of debt recycling lies in its systematic approach:
- Utilizing surplus finances to pay down home loans.
- Unlocking the equity within your property.
- Reinvesting this equity into revenue-generating assets.
This transforms a part of your home loan debt into an investment debt, which can then benefit from tax deduction claims related to interest payments and associated investment costs.
The outcome? You use investment returns to fast-track your mortgage repayment, thereby boosting your net worth rapidly. Essentially, you're repurposing your mortgage debt into investments that yield returns.
Benefits at a Glance
- Speeds up wealth accumulation via investment using borrowed funds.
- Creates avenues for passive income through investments.
- Optimizes tax deductions on interest expenditure.
Who Is Debt Recycling Ideal For?
Debt recycling shines for:
- Property proprietors who can harness property equity.
- High-income individuals who can substantially benefit from tax deductions due to their tax bracket.
Pre-Start Considerations
Despite its lucrative nature, debt recycling does involve considerations:
- Your risk appetite – the process entails market risks.
- Your current debt standing – ensure manageability before increasing liabilities.
- Your investment acumen – you should be adept at or willing to learn about portfolio management.
Risks vs. Rewards
Debt recycling is a balancing act between the following:
- Market Risks: Market swings can affect the capital invested.
- Interest Rate Risks: Escalations in interest rates could affect repayment capabilities.
Counter these with:
- Strategic Asset Selection: Opt for assets with potential for steady growth.
- Regular Portfolio Reviews: Keep an eye on your investments and adjust strategies as needed.
- Professional Consultation: Engage with financial experts to tailor a debt recycling plan that fits your profile.
A Stepwise Guide to Begin
- Assess how much you can safely borrow.
- Establish a flexible lending mechanism, like a line of credit.
- Channel extra funds towards reducing your home loan.
- Use the built-up equity for investment.
- Select income-generating, tax-efficient assets for investment.
- Capitalize on tax deductions linked to your investment debt.
Success Tips for Debt Recycling
- Start cautiously with manageable debt portions.
- Establish clear financial objectives and review them periodically.
- Maintain a long-term perspective on your investment strategy.
- Keep meticulous records of all related financial transactions.
- Seek advice from professionals to customize your debt recycling approach.
Debt recycling step by step
- Split your home loan. Keep the non-deductible home loan separate from any new investment borrowing, so the purpose of each dollar is clear.
- Pay down the home loan. Put spare cash, and later investment income, against the home loan.
- Redraw for investment only. Draw the same amount from a separate split and use it only to buy income-producing assets, such as an investment property or shares.
- Repeat. Over time, more of your debt is linked to investments and less to your home.
- Review every year with your accountant, especially when rates or tax rules change.
Interest is generally deductible only when the borrowed money is used to earn assessable income, so keeping the loan splits clean is what makes the strategy work. Model the numbers with our debt recycling calculator.
Is debt recycling right for you?
- Stable income: you can keep up repayments if rates rise or an investment underperforms.
- Equity in your home: you have a home loan to pay down and equity to borrow against.
- A long time frame: the strategy relies on investments growing over many years.
- Comfort with borrowing: you understand that borrowing to invest magnifies losses as well as gains.
Managing the risks
- Keep a cash buffer for vacancies, repairs and rate rises.
- Track each investment's income, costs and value, and stop recycling if the numbers stop working.
- Keep records that show how every redraw was used, in case the ATO asks.
- Get licensed financial and tax advice before you start.
Conclusion
Debt recycling is an innovative way to turn a typical mortgage into a catalyst for wealth creation, leveraging the potential of investments like shares and real estate to build wealth. With judicious planning and astute financial maneuvers, it can significantly fast-track financial growth and passive revenue generation.
For those aiming to optimize their investment property potential, consider reaching out to Duo Tax for a complimentary discussion on making the most of your tax deductions through depreciation.
FAQ Corner
- Debt Recycling Example? Imagine accelerating your mortgage payments while concurrently securing a line of credit against your home for investment in shares or property, creating tax-deductible debt.
- Debt Recycling vs. Negative Gearing? While both involve tax benefits, negative gearing primarily relates to absorbing losses for tax deductions, whereas debt recycling strategically converts debt for wealth accumulation.
- Drawbacks? Potential disadvantages include heightened debt responsibilities, market exposure, interest rate sensitivities, and setup costs for lending mechanisms.
- What is 'Recycling' the Loan? It means re-purposing your mortgage repayments into investment funds, transitioning personal debt into tax-advantaged investment debt over time.
Are you a financial planner or adviser with clients buying property? See how financial planners refer clients to our buyers agents.

Written by
Mossy Taheri is the founder and director of Rising Returns, a licensed buyers agency. He has 11 years in the property industry and leads the research behind every purchase, from market selection to negotiation.
Rising Returns is a licensed buyers agency, not a financial adviser, and does not hold an Australian Financial Services Licence. This article is general information only, not financial, tax or legal advice. It does not take into account your objectives, financial situation or needs. Consider seeking advice from a licensed financial adviser, accountant or lawyer before acting.